

Greenlight: For Families

- 10.87K Reviews
- 4.7
- Downloads
- 1,000,000+
Our take on Greenlight: For Families from Appgk
When I look at a family finance app, I do not judge it only by whether a child can tap a card at a checkout. I want to know whether the whole household can use it without confusion: whether parents understand what they are managing, whether children can see a clear connection between spending and responsibility, and whether the arrangement still feels practical after the novelty wears off. That is the lens I used with Greenlight: For Families, a finance app from Greenlight Financial Technology, Inc. built around a debit card for children and teenagers that parents manage through an app.
The appeal is easy to understand. Instead of handing over cash, sharing a bank card, or relying on a child’s vague promise to remember every purchase, a parent can make the payment arrangement part of a more visible household routine. The app is free to install, carries an Everyone age rating, and is available for devices running a recent enough operating system. Its store presence is substantial, with more than a million installs, an average rating of 4.7, and roughly eighty-five thousand ratings, so it is clearly not a niche experiment.
How it feels in a shared household
The most convincing use case is a family in which one parent handles most financial tasks but another adult still needs to understand what is happening. A child may need money for lunch, transport, school supplies, or an occasional activity, while the adults want a consistent way to provide it. In that setting, the app is more useful than a loose mixture of cash, messages, and last-minute transfers because the card and the parent-managed app create a single point of reference.
I would not treat it as a replacement for every family conversation. The app can organize the practical side of giving a child spending access, but it does not decide what your household considers responsible spending. Parents still need to agree on expectations, and children still need explanations that make sense at their age. The strongest experience comes when Greenlight is used as a tool for those conversations rather than as an automatic substitute for them.
Best Parts of Greenlight: For Families
Things to Keep in Mind About Greenlight: For Families
A realistic weekday example shows where the arrangement helps. A teenager leaves for school with enough money available for an ordinary meal and knows that the parent can manage the account from the phone. If plans change and the teenager needs to buy something unexpected, the household has a more traceable method than passing around a physical bank card. Later, the purchase can become part of a calm conversation about planning, priorities, and whether the amount provided matches the child’s actual routine.
That same scenario also reveals an important boundary. The app does not remove the need for backup thinking. Families should decide what happens if a phone is unavailable, a card is misplaced, or a child encounters a situation that requires an adult’s help. I prefer setting those rules before the first real outing. A finance app can support coordination, but it should not become the only communication channel between a child and a parent.
News and Features Related to Greenlight: For Families

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Starting with clear account boundaries
Setup is easier when adults first decide who is responsible for what. One parent may be the main manager, while another needs visibility or involvement in everyday decisions. Before creating routines, I would write down which adult handles funding, which adult answers questions, and which adult speaks with the child about spending. This simple division prevents the common household problem where everyone assumes someone else checked the situation.
The child’s role should be equally clear. A debit card can feel like unrestricted money even when the parent sees it differently. I would explain whether the card is intended for regular spending, specific needs, or a mixture of both. I would also agree on what the child should do before making an unusual purchase. These boundaries are more important than any single screen in the app because they determine whether the child experiences the card as a learning tool or merely as a convenient payment method.
Don't want to read the full review?
Families using a shared tablet or a device that moves between adults should be especially careful about account boundaries. Financial information should not be treated like a casual shared profile. I recommend keeping the parent side associated with the appropriate adult, avoiding casual handoffs while an account is open, and making sure children use only the part of the experience intended for them. This is not a criticism unique to Greenlight; it is a sensible habit for any household finance service.
Another useful preparation step is to establish a small vocabulary. Decide what the family means by “available,” “reserved,” “spent,” and “needs approval,” if those ideas are part of your household rules. Children often understand money better when adults use the same words every time. The app can show the financial activity, but consistent language is what turns that activity into a lesson a child can remember.
Screenshots
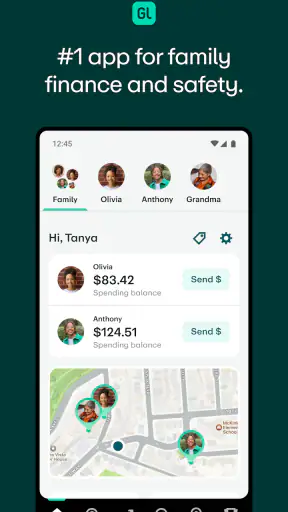
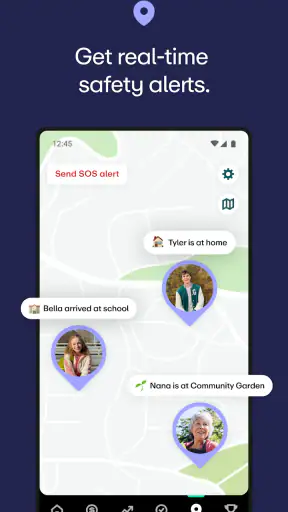
Coordinating money without creating extra friction
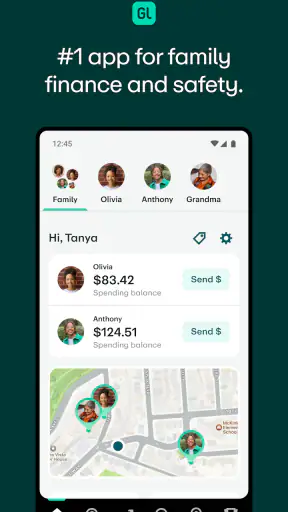
The app’s central strength is coordination. A parent-managed debit card gives the household a more structured alternative to repeatedly sending money through unrelated payment services or letting a child use an adult’s card. The arrangement can make everyday decisions easier to discuss because the money intended for the child is separated from the parent’s general spending activity.
That separation is valuable in families with more than one child, but it also requires discipline. I would avoid treating every child’s arrangement as identical simply because the app is the same. A younger child may need tighter guidance and more frequent conversations, while an older teenager may need a broader spending routine and more responsibility. The useful comparison is not whether every child receives the same setup; it is whether each child understands the rules attached to their own situation.
For shared households, a weekly check-in can work better than constant monitoring. The parent can review what happened, ask about anything unusual, and adjust the next period’s plan if necessary. This approach avoids turning every small purchase into an interrogation while still keeping the adult involved. It also gives the child a chance to explain context that a transaction alone cannot show.
I see a trade-off here. Visibility can reduce uncertainty, but too much attention can make a teenager feel watched rather than trusted. Parents should decide what information genuinely needs discussion and what can remain part of normal independence. If every purchase becomes a test, the app may create tension even though the underlying financial arrangement is sound.
Greenlight is also more focused than a standard banking app used by an adult. A typical bank account may be better for a parent who wants a broad set of personal banking services in one place, while a peer-to-peer payment app may be quicker for occasional transfers between adults. Those alternatives can be more convenient for isolated payments, but they do not necessarily provide the same family-centered structure. I would choose Greenlight when the goal is an ongoing parent-and-child spending arrangement, not merely sending money once.
Matching the experience to age and trust
The store rating of Everyone makes the app approachable from an age-classification perspective, but that should not be confused with a universal recommendation for every child. A child’s reading ability, judgment, comfort with payment cards, and understanding of personal information matter more than a label alone. Parents should introduce the system at a pace the child can handle.
For a younger child, I would keep the explanation concrete: what the card is for, where it can be used in ordinary life, and when to ask an adult. The parent may need to review activity together with the child and connect purchases to simple choices. For a teenager, the more useful discussion may involve planning ahead, distinguishing an impulse from a need, and taking responsibility when a mistake happens.
Trust should grow gradually rather than being granted all at once. A parent can begin with a narrow purpose, such as school-day spending, and broaden the arrangement only after the child shows that they understand the household rules. This is one of the most practical ways to use the app: treat access as part of a learning progression, not as a binary decision between total control and total freedom.
I would also avoid using the app as a punishment system unless the family has discussed that approach carefully. Removing access may solve an immediate disagreement, but it can make money feel unpredictable if the rules change without explanation. A more constructive routine is to discuss the behavior, restate the expectation, and make any change deliberately. The technology is strongest when it supports predictable boundaries.
Parents should remember that a child’s financial education includes more than spending. Saving, generosity, comparison shopping, privacy, and recognizing suspicious requests all belong in the conversation. Greenlight can be the practical setting for those lessons, but the adult still supplies the judgment and context. That is why I see the app as most valuable for involved parents, not for households hoping an app will teach money management by itself.
Where the experience can feel limited
The parent-managed design is also the source of its main limitation. Adults who want a completely independent account for an older teenager may find the family structure too involved. If your priority is giving a young adult a conventional banking relationship with minimal parental participation, a regular bank account may fit better once the child is ready for that responsibility.
There can also be household friction when adults disagree about the arrangement. One parent may prefer strict oversight while another favors more freedom. Greenlight cannot resolve that disagreement; it may simply make the difference more visible. I recommend settling the family policy first, including who makes final decisions, so the child is not placed between conflicting instructions.
Another limitation is psychological rather than technical. A card can make spending feel effortless, especially for a child who rarely handles cash. Parents should deliberately preserve moments where the child checks a balance, thinks about a purchase, or explains a choice. Without those habits, the app may improve convenience without improving understanding.
The app is not the best fit for someone searching only for a simple way to reimburse another adult. It may also be unnecessary for a family that already has a straightforward cash allowance system and does not need a managed card. In those cases, adding a finance app could introduce another account to maintain without solving a real problem.
Device compatibility is another practical checkpoint. The current version is 8.6.0 and the minimum operating system is 10, so I would check the phone or tablet before planning the household around it. That is a small step, but it matters when a child depends on the card and the parent depends on the app at the same time.
Small habits that make it work better
My first tip is to begin with a written family agreement, even if it fits on a single page. Include the card’s purpose, the situations that require a conversation, what the child should do if something goes wrong, and how often the household will review spending. This removes ambiguity that no interface can fix.
My second tip is to use real routines rather than abstract lessons. Discuss the money before a school trip, after a change in timetable, or when the child starts managing a new kind of expense. Those moments give the card a clear purpose and help the child connect digital payments with physical needs.
My third tip is to separate review from blame. Looking at activity should answer practical questions: Was the amount enough? Did the child encounter an unexpected cost? Does the routine need adjusting? If every review is framed as a search for wrongdoing, the child may hide problems instead of asking for help.
A fourth useful habit is to involve every adult who genuinely needs to coordinate, but not to turn access into a free-for-all. Shared-device households benefit from a clear primary manager and a known backup adult. That arrangement reduces duplicated decisions and makes it easier for the child to know whom to contact.
Finally, revisit the arrangement as the child matures. A setup that works for a younger child can feel restrictive later, while a generous arrangement introduced too early can be confusing. The card should remain connected to the child’s actual responsibilities, not to an old rule that nobody has reviewed.
My household verdict
After looking at the app as a family finance tool rather than simply a payment card, I think Greenlight is a strong choice for parents who want a visible, ongoing way to introduce children and teenagers to spending responsibility. Its free price lowers the barrier to trying it, and its broad adoption and 4.7 average suggest that many families find the overall approach useful. The developer, Greenlight Financial Technology, Inc., has positioned it clearly around parent-managed access rather than ordinary adult banking.
I would recommend it to a household that values coordination, wants to reduce reliance on cash or an adult’s personal card, and is willing to stay involved. It is particularly suitable when parents want everyday purchases to become opportunities for practical money conversations. The best results will come from families that set boundaries, protect account access on shared devices, and gradually adjust trust as the child gains experience.
I would skip it if you want a fully independent account, only need occasional transfers between adults, or do not want to discuss spending with your child. In those situations, a conventional bank account or a simpler payment method may be less complicated. Greenlight is not valuable because it makes parenting automatic; it is valuable because it gives an involved household a dedicated structure for a responsibility that otherwise tends to become scattered.
My final view is positive, with one condition: use the app as part of a family system. The card handles convenience, the parent-managed experience supports coordination, and the conversations provide the actual education. When those three pieces work together, the app becomes more than a way to pay—it becomes a practical bridge between parental guidance and growing independence.
For families ready for that shared responsibility, Greenlight deserves serious consideration. For everyone else, the right question is not whether it has enough features, but whether a managed child-and-parent arrangement matches the way your household already makes decisions about money.
Greenlight: For Families FAQ
What is Greenlight: For Families?
Greenlight: For Families is a family-focused financial app designed to help parents manage children’s spending, saving, and money habits from one place. Parents typically control the account, set spending limits, assign chores or allowances, and monitor transactions, while children use an associated card and app experience. Availability and specific features may depend on the selected Greenlight plan and region.
How does the Greenlight card work for children?
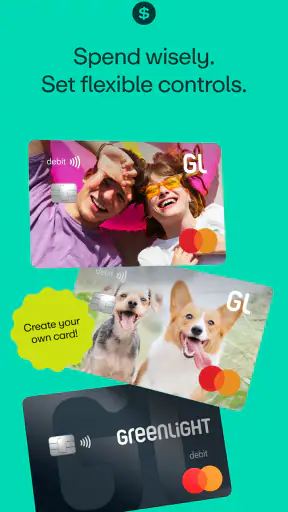
The Greenlight card is a reloadable debit card connected to the family account rather than a traditional credit card. Parents add money, decide where the card can be used, and can receive transaction notifications. Spending controls may include merchant categories, limits, and the ability to pause the card. Before downloading, parents should review fees, supported locations, and the current terms for card usage.
Is Greenlight: For Families safe for children to use?
The app is built around parental supervision, allowing adults to review purchases, manage permissions, and teach responsible money use without giving children unrestricted access to a bank account. Security still depends on protecting login details, enabling available account safeguards, and discussing safe card use with children. Parents should also check the company’s privacy policy and age requirements.
Does Greenlight: For Families charge a subscription or other fees?
Greenlight: For Families generally operates through paid membership plans, and the price can vary according to the package, promotions, billing cycle, and number of children included. Some services or optional features may have separate conditions, while card replacement or other transactions could involve additional charges. Check the latest pricing page in your country before creating an account.
What devices and family members can use Greenlight: For Families?
Greenlight: For Families is intended for compatible Android and iOS devices, with parents and children using the parts of the service assigned to them. The exact operating-system requirements, supported countries, number of children, and account eligibility can change over time. Families should confirm device compatibility, download the official app, and make sure every user meets the stated age requirements.











